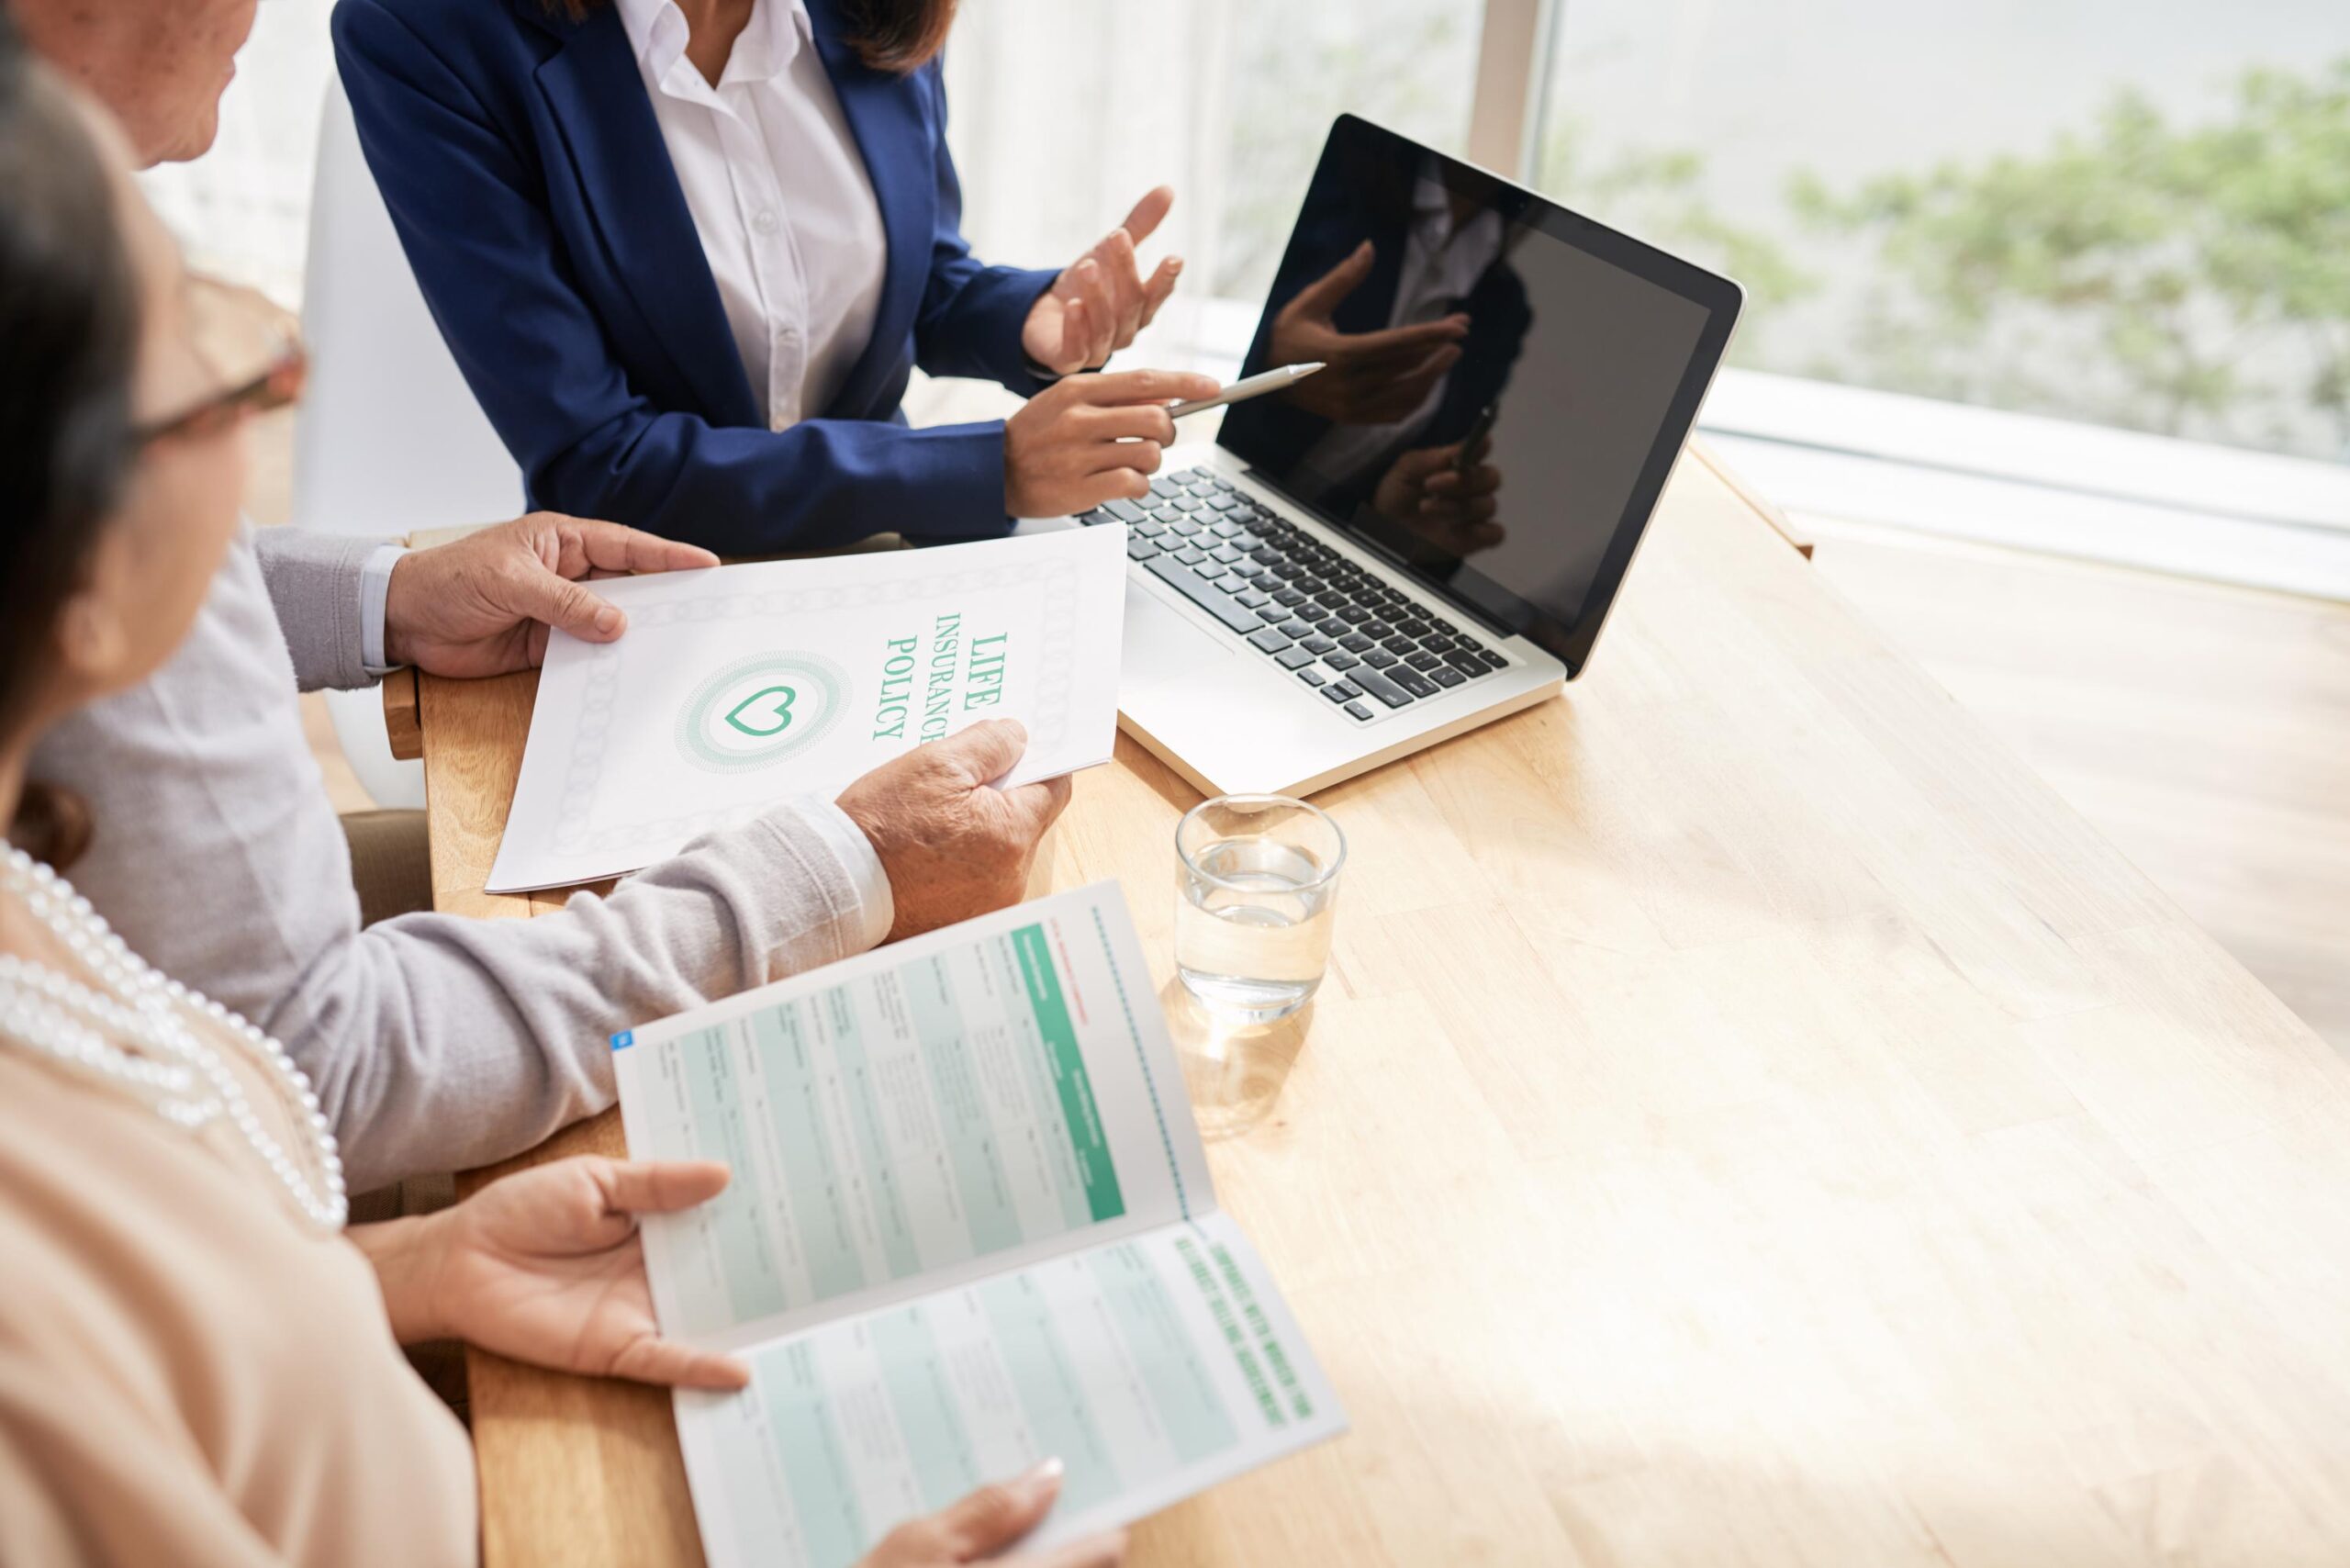
Many people think life insurance only pays out after death. But what if it could help replace your income during illness or protect your wealth while you’re still alive? Living benefits offer real financial support when you face chronic, critical, or terminal illnesses. This guide explains how life insurance living benefits fit into your protection plan, helping families and business owners secure income and preserve assets. Book a free 20-minute strategy call to see if living benefits fit your plan.
Understanding Living Benefits
Living benefits can seem complex, but they offer crucial support during life’s toughest challenges. They provide financial aid when you face serious health issues, helping you focus on recovery instead of financial stress.
What Are Living Benefits?
Living benefits refer to features in some life insurance policies that provide financial help while you’re still alive. They kick in during chronic, critical, or terminal illnesses. This means if you face a health crisis, you might access funds from your policy to cover medical bills and other expenses. It’s a safety net that ensures you’re not just protected after passing but also while you’re living. For instance, a chronic illness rider might pay out if you can’t perform daily activities, easing the burden on family finances.
Key Riders Explained
Riders are additional benefits added to your life insurance policy to enhance coverage. The critical illness rider offers a payout if you’re diagnosed with severe conditions like cancer or heart disease. Similarly, a terminal illness rider provides access to funds if a doctor believes you have 12 months or less to live. These riders transform your life insurance into a versatile tool, providing immediate financial relief and protecting your wealth. Most people think life insurance is only about death benefits, but these riders show its true potential in living scenarios.
Benefits for Families and Owners
Living benefits are invaluable for families and business owners alike. They ensure financial stability during health challenges, preventing the depletion of savings. Imagine facing a serious illness without worrying about lost income or business disruptions. For business owners, having a key person insurance can be crucial. It supports business continuity by securing funds to manage operations if a vital team member falls critically ill. This proactive planning helps protect both personal wealth and business assets.
Enhancing Protection Planning
Including living benefits in your insurance strategy enhances protection planning. It offers a comprehensive approach to securing both your income and assets during unforeseen events.
Income Protection Strategies
Income protection becomes vital when life throws unexpected challenges. With living benefits, your insurance policy can replace lost earnings if illness prevents you from working. This means your lifestyle and financial goals remain intact. For those running a business, it acts as a financial cushion during times when you’re unable to generate revenue. It’s like having an emergency fund that kicks in during critical times, providing peace of mind to continue focusing on recovery.
Wealth Preservation Tips
Preserving wealth is about more than saving money. It’s about ensuring your assets remain secure even when health issues arise. Living benefits help by covering significant medical expenses, protecting your savings from being drained. Instead of using savings or retirement funds, your policy steps in to handle costs. This strategy supports long-term wealth growth by keeping your financial plan on track, despite unexpected bumps in the road.
Role in Business Continuity
For business owners, living benefits play a crucial role in continuity planning. They provide funds to keep operations running smoothly if illness strikes a key member. A buy-sell agreement funding can ensure business ownership transitions seamlessly, avoiding disruptions. This kind of strategic planning safeguards your business’s future, maintaining stability and protecting your personal financial interests. Having a safety net like this prevents common pitfalls and keeps your business resilient.
Steps to Integrate Living Benefits
Integrating living benefits into your financial strategy requires thoughtful planning and evaluation. Here’s how you can effectively incorporate these benefits into your protection plan.
Evaluating Your Needs
Start by assessing your current and potential future needs. Consider your health, family responsibilities, and financial goals. Long-term care alternatives might be essential if you anticipate needing extended medical support. Determine what riders best suit your situation. Consult a Long Island financial advisor for tailored advice, ensuring your policy aligns with your unique circumstances. This evaluation sets the foundation for a robust protection plan.
Choosing the Right Riders
Choosing the right riders involves understanding what each one offers and how it fits into your life. A chronic illness rider might be beneficial if you have a family history of long-term health issues. Consider the costs and benefits of each rider, balancing immediate needs with future possibilities. Discuss options with a financial expert to ensure you’re making informed decisions that enhance your overall strategy. The right riders provide targeted protection, enhancing your policy’s value.
Planning for Tax Efficiency
Tax efficiency is a critical aspect of financial planning. Consider how living benefits impact your tax situation. Work with a professional to structure your policy in a way that maximizes tax benefits. This might involve tax-efficient insurance strategies that protect both your current income and long-term wealth. Thoughtful planning ensures that every dollar works harder for you, reducing tax liabilities and increasing financial security.
Frequently Asked Questions
What are living benefits in life insurance?
Living benefits are features in life insurance policies that provide financial support during serious health issues like chronic, critical, or terminal illnesses. They allow policyholders to access funds needed for medical expenses, ensuring financial stability while managing health challenges.
How do living benefits support business continuity?
Living benefits can secure funds to maintain operations if a critical team member falls ill. This financial cushion enables smooth business continuity, protecting against disruptions and ensuring vital business activities continue.
Why are riders important in a life insurance policy?
Riders enhance a policy by adding specific benefits like critical illness coverage. They tailor the policy to fit individual needs, providing targeted protection against potential risks, and ensuring comprehensive financial security.
How can living benefits help in preserving wealth?
Living benefits cover significant medical expenses, preventing the depletion of savings. By protecting assets from being drained, they help maintain long-term growth and financial stability, ensuring your wealth preservation plan stays on track.
What should I consider when integrating living benefits into my plan?
Evaluate your current and future needs, understand each rider’s benefits, and choose what suits your situation. Consult a financial advisor for tailored advice and plan for tax efficiency to maximize the benefits of your living benefits strategy.